Fifty Sets of Rules: How Your State Shapes Crypto Custody, Inheritance, and Legal Recourse
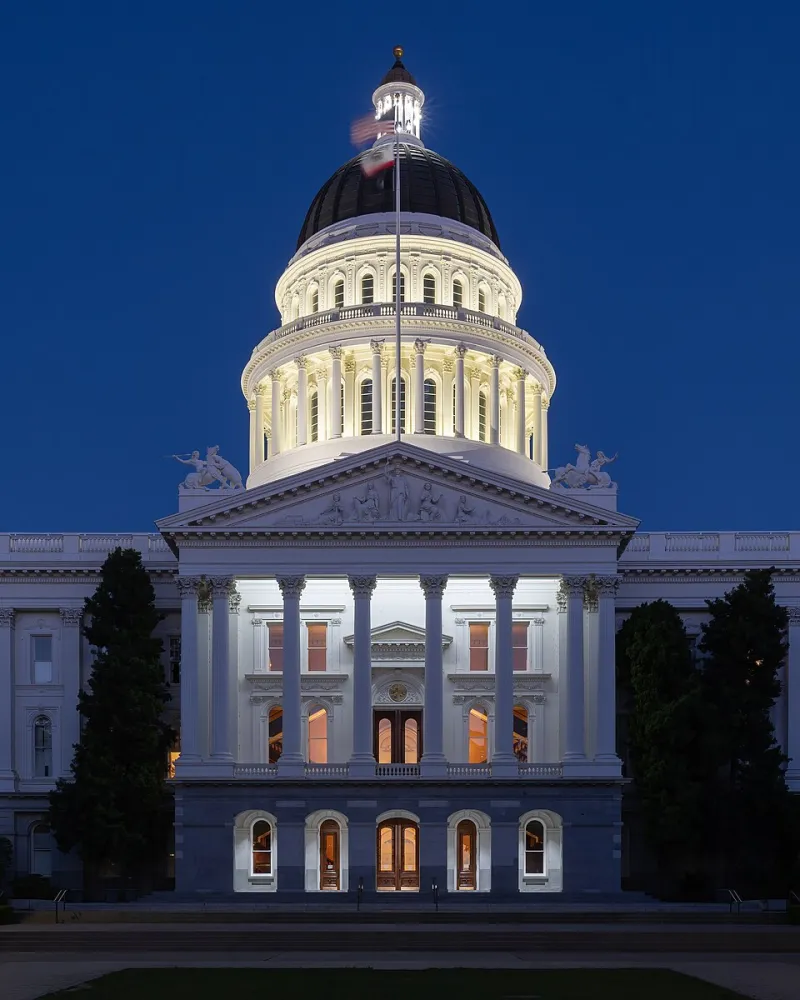
Photo: Frank Schulenburg, CC BY-SA 4.0, via Wikimedia Commons
Ask most American crypto holders which laws govern their wallets and they'll point to Washington, D.C. — the SEC, the CFTC, IRS guidance. That's only half the picture. Some of the rules with the most direct impact on your day-to-day custody, your estate plan, and your recourse when things go wrong are written in state capitols, and they vary dramatically from one border to the next.
Why State Law Matters for a Borderless Asset
Cryptocurrency doesn't respect geography, but property law does. When you die, when a custodian fails, when an exchange freezes withdrawals, or when a dispute lands in court, the governing framework is usually determined by where you live — not where the blockchain lives.
Inheritance: The Patchwork Problem
Digital assets occupy awkward territory in estate law. A few states have modernized explicitly:
- Wyoming led the nation with its 2019 digital asset statutes, classifying digital assets as property and creating clear frameworks for banks to custody them. It also pioneered the DAO and special-purpose depository institution structures.
- The Revised Uniform Fiduciary Access to Digital Assets Act (RUFADAA) has been adopted in some form by the vast majority of states, giving executors and fiduciaries a legal pathway to access digital accounts — but its application to non-custodial wallets depends heavily on whether your heirs hold the keys.
Here's the practical reality: RUFADAA gives your executor authority over your accounts, but a self-custodied wallet has no account to hand over — only keys. If your heirs don't hold or can't find your seed phrase, no state law can unlock the chain. States can grant fiduciary access; they cannot recover a private key. This is why estate documents alone are insufficient, and why documentation of key locations (secured, separate from the will itself) matters in every state.
Custody and Consumer Protections
State money transmitter laws are where crypto consumers most often encounter their state government:
- New York requires a BitLicense for virtual currency businesses — among the strictest regimes in the country, which is why some major platforms simply don't serve New Yorkers.
- Wyoming and Texas have taken permissive approaches, with Texas expressly recognizing that state-chartered banks may custody digital assets.
- California moved in 2024 to establish a comprehensive digital financial asset framework under its Department of Financial Protection and Innovation, replacing a patchwork of money transmission rules.
These regimes matter most when a custodian fails. In the Celsius and Voyager bankruptcies, state regulators pursued different remedies on different timelines — and customers in different states experienced materially different outcomes and recovery processes.
Self-Custody Itself: Increasingly Explicit
A growing number of states have passed statutes affirming the right to self-custody digital assets and protecting activities like running nodes and mining from restrictive zoning or licensing. States including Wyoming, Oklahoma, Missouri, and Arkansas have enacted such protections. In states without them, self-custody remains lawful everywhere — but the affirmative legal foundation is thinner, leaving more room for regulatory interpretation.
What This Means for You, Wherever You Live
Regardless of your state, four actions are universally prudent:
- Put crypto in your estate plan explicitly. Generic wills written before 2015 rarely address digital assets at all. Work with an attorney familiar with RUFADAA in your state.
- Separate knowledge from location. Your will should reference the existence of a key inventory, not contain the keys themselves — wills become public record in probate in many states.
- Know your custodian's charter. If you use any service, check whether it's licensed as a money transmitter in your state and what that license actually promises (hint: usually very little — deposits are typically not FDIC-insured).
- Keep records for federal purposes regardless. IRS reporting obligations are uniform across all fifty states, and state income taxes on crypto gains follow your residency.
The Direction of Travel
The trend is toward clarity, but not uniformity. More states are codifying digital asset property rights and self-custody protections each legislative session, while a handful maintain restrictive licensing regimes that shape which services residents can access. Until federal legislation resolves the gaps, your legal standing as a crypto holder is, in significant part, a function of your address.
For self-custody holders, the encouraging throughline is consistent: states are converging on the view that holding your own keys is a protected form of property ownership. The responsibility that comes with it — especially planning for what happens to those keys — remains entirely yours.